Build an approval‑ready credit profile
Understand what’s driving your credit decisions, identify items that may be unfair or inaccurate, and take a structured next step toward stronger approvals and better terms.
Built around established U.S. credit reporting practices and dispute procedures under the Fair Credit Reporting Act (FCRA). No unrealistic promises—just clarity, documentation, and structured credit improvement.
Unlock more options
Choose the outcome you care about. We’ll outline what improves it—and what to watch for—so you can move forward with confidence.
Your path to stronger credit
A stronger credit profile can mean better approval odds, improved loan terms, and more financial flexibility. Get a clear, no-fluff overview of what credit improvement can help you achieve — then take the next step when you're ready.
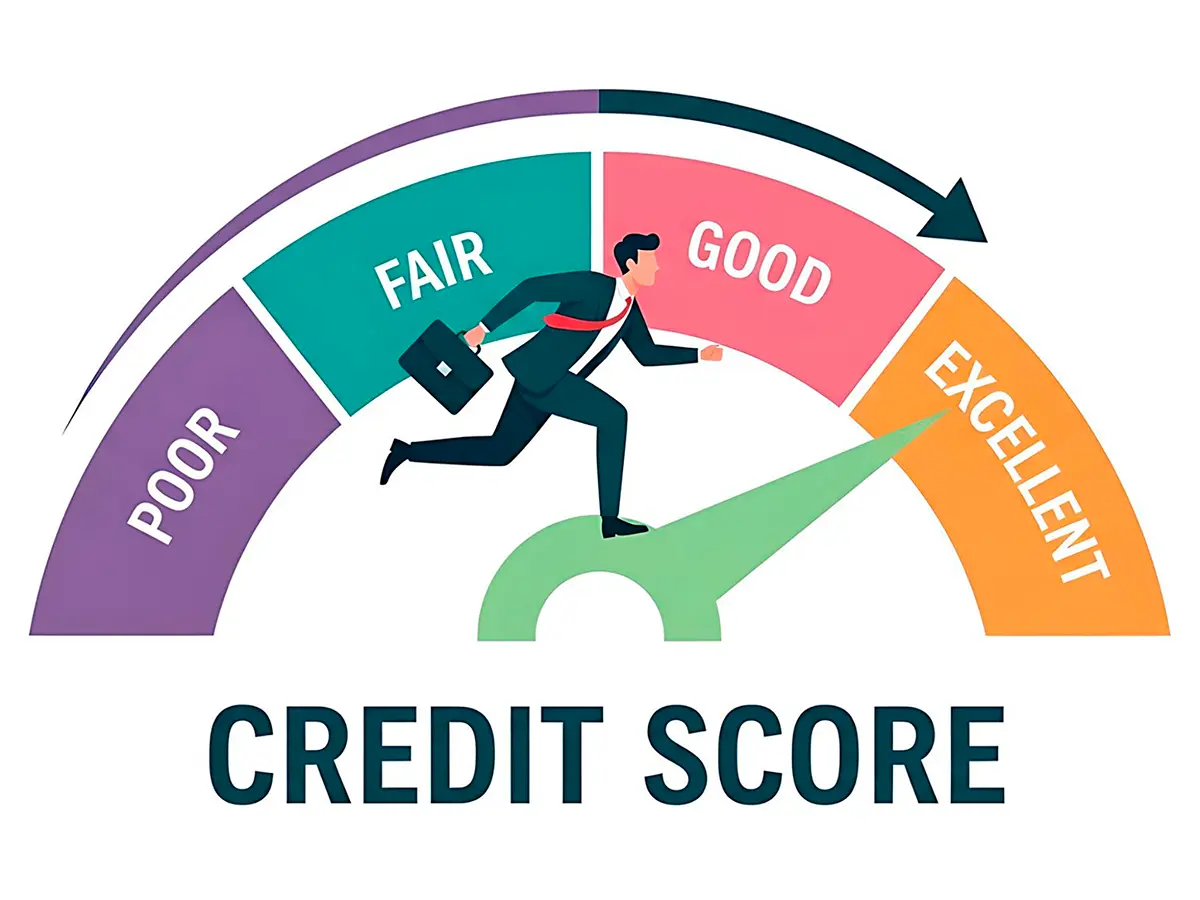
Credit decisions in the U.S. are typically influenced by payment history, utilization ratios, account age, recent inquiries, and the accuracy of reporting across major credit bureaus.
Even small inconsistencies can affect lending algorithms. A structured credit improvement approach focuses on verified data, responsible usage patterns, and consistent financial behavior.
*Results vary. This page does not guarantee outcomes.
How it works
A straightforward workflow used by reputable credit‑support programs: review, challenge what’s questionable, and build stronger habits while updates are processed.
Review your starting point
Clarify your goal and look at what’s currently affecting approvals and terms.
Identify what can be challenged
See what information is typically needed, what to expect next, and how the workflow usually looks.
Move forward
Continue to explore available options and take the next step toward better credit outcomes.
ways to build your credit score, ranked by effort and impact
This selection framework focuses on moves that are convenient yet measurably effective. Start with actions that improve payment history and lower revolving utilization, then layer on strategies that diversify accounts and minimize friction.
What actually moves the score
- Payment history (largest factor): On-time payments build trust; missed payments linger.
- Credit utilization: The percent of credit you use on revolving lines; lower is better.
- Age of credit: Older, well-managed accounts help; frequent resets hurt.
- Account mix: A blend of revolving (cards) and installment (loans) adds depth.
- New credit/inquiries: Too many hard pulls in a short window can ding temporarily.
Quick, convenient wins
- Autopay the minimum; schedule an early payoff: Set autopay to the minimum to guard against slips, then pay the remaining balance before the statement date to both avoid interest and cut reported utilization.
- Time payments for the statement date: Many scores read your balance as of the statement. Aim to report under 30% - actually, more precisely, under 10% yields consistently stronger results without extra effort.
- Request a credit line increase (soft pull only): A higher limit lowers your utilization denominator. Use the issuer's app to check if it's a soft inquiry first.
- Dispute clear errors: One inaccurate late mark or collection can overshadow years of good data. Pull reports and challenge verifiable mistakes with the bureaus.
- Set due-date reminders: Calendar nudges 3 - 5 days ahead keep streaks intact, especially across multiple cards.
- Keep small recurring charges on one low-limit card: It simplifies monitoring and prevents an accidental high utilization spike elsewhere.
Building from a thin or damaged file
- Secured credit card: A refundable deposit creates a line that reports monthly. Keep usage light and pay early.
- Credit-builder loan: Fixed, predictable payments add installment history; funds are released at the end.
- Authorized user status: Being added to a well-aged, low-utilization account can transmit age and positive history; confirm the issuer reports AU data.
- Report recurring payments: Rent and telecom reporting services can add on-time data points to thin files.
- Do not close your oldest card: Even dormant, its age supports your average account length.
A small, real-world usage moment
During a commute, I opened my card app, checked the statement date, and paid down the balance two days early. Nothing dramatic - just a five-minute habit. The next cycle's report reflected lower utilization, and the score tracked upward accordingly.
Application cadence and guardrails
Batch hard inquiries sparingly - ideally one account every few months - and use soft-pull prequalification. Space out new lines so your average age stabilizes, and let a fresh account mature before opening another.
Maintenance and measurement
- Monitor all three reports quarterly: Catch errors and new accounts fast.
- Use free score updates: Trend direction matters more than any single number.
- Keep an emergency buffer: Avoid carrying balances that force interest.
- Differentiate "balance" from "reported balance": You can pay in full yet still report high if you pay after the statement; timing fixes this.
- Set alerts for utilization thresholds: Many apps ping when usage crosses 10% or 30%.
Select the lowest-effort tactics you can repeat, automate what you can, and let time compound the result.
Learn the basics of how to build credit, how to use credit cards and practice positive credit behavior.
A strong credit score is a key that can unlock opportunities, like lower interest rates and better borrowing terms. It's a three-digit ...
Create a plan - Contact all creditors. - Pay off delinquent accounts first, then debts with higher interest rates; you may save money - Consider a debt ...
Frequently asked questions
A clear next step — without the guesswork
See what’s impacting approvals and what may deserve a closer look.
Understand how disputes are structured and what documentation matters.
Improve utilization, consistency, and long-term credit stability.
See what improving your credit could change
Take a structured next step based on your current profile — and decide with clarity.